What’s Hatching
- Shout out to our Client Services Manager, Laura Modjeski, who is celebrating her 19th anniversary with our Two Bird team! Thank you for all your hard work and dedication throughout the years!!
- Open enrollment season is right around the corner! Many employer benefit windows open in the fall, and people often default to last year’s choices without a second look. Health plan options, FSA elections, and life insurance coverage are all worth a fresh set of eyes, and your Wealth Strategist can help make sense of the options at hand. Don’t hesitate to reach out and schedule a time to connect!
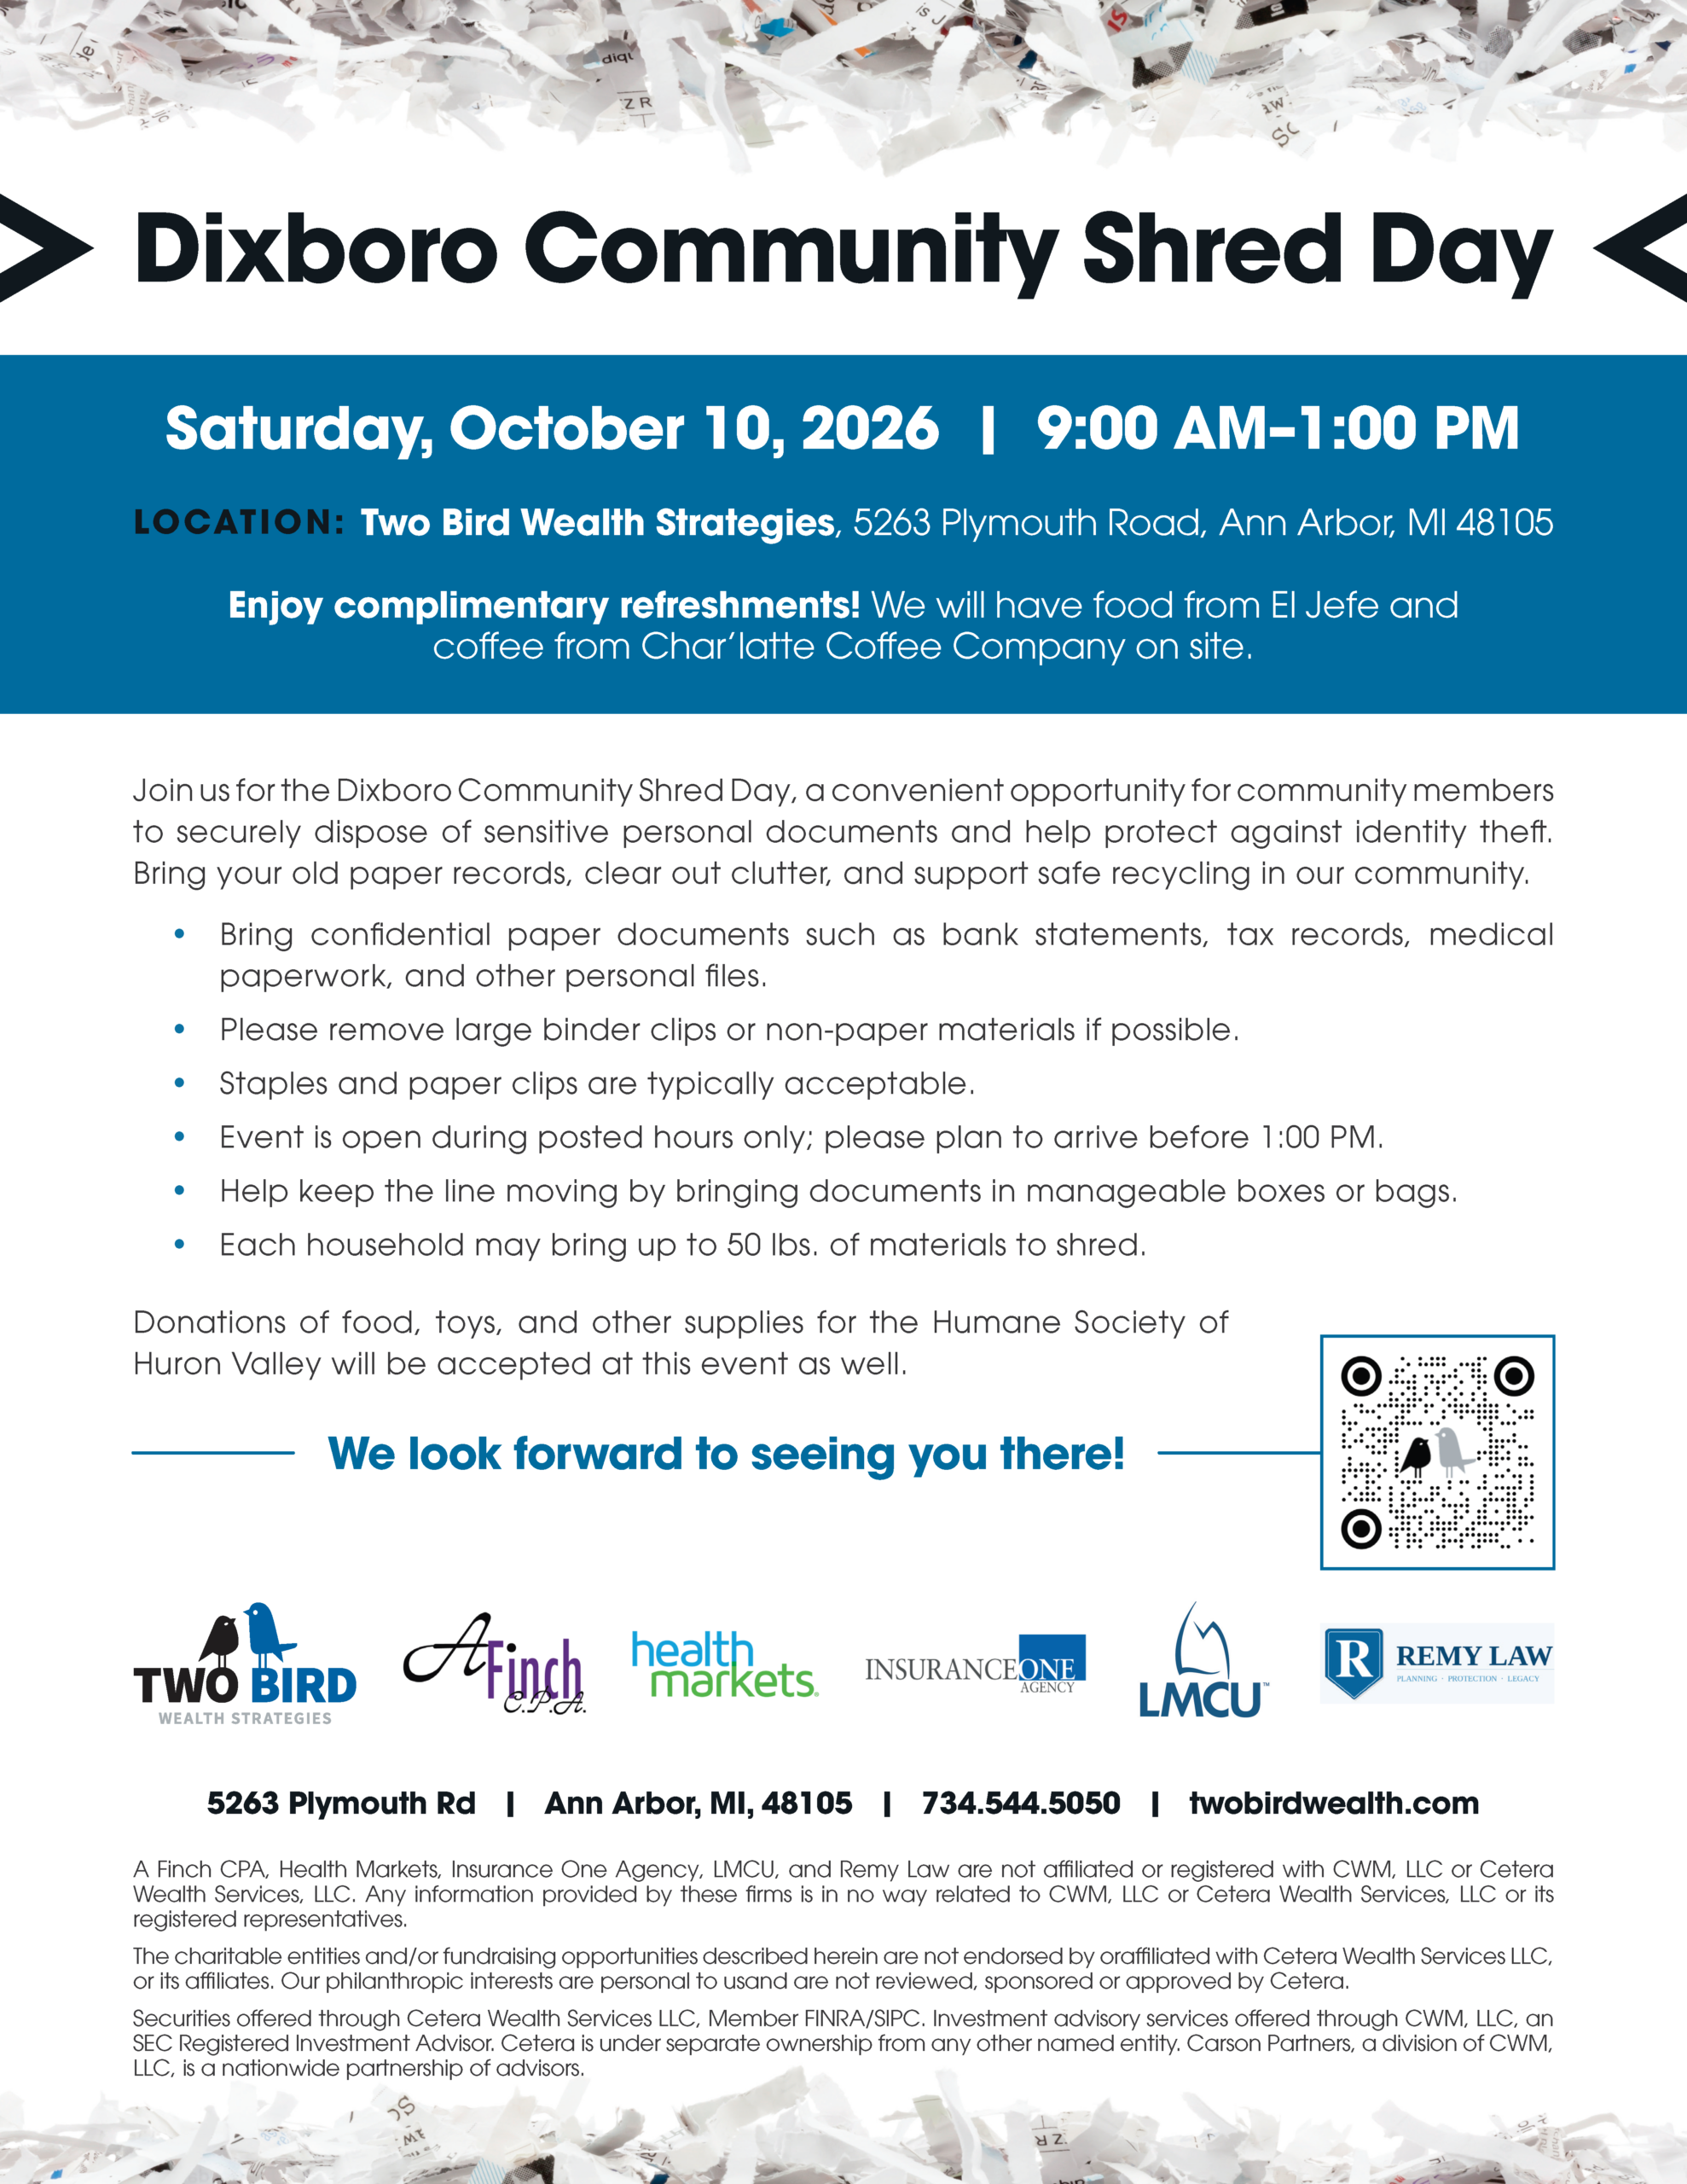
- Shred Day details! 10-10-2026 — Don’t miss out on this opportunity to securely dispose of sensitive documents and join in some community fun. More details below!
Welcome back to Bird’s-Eye View!
This month we’re covering Medicare in advance of the upcoming enrollment period.
Read on for our insights that are intended for those initially approaching enrollment or already using Medicare. Between our team and our special guest author, we hope you’ll find some important reminders and insightful guidance.
Hello, Baby! Welcome Back, Erin!
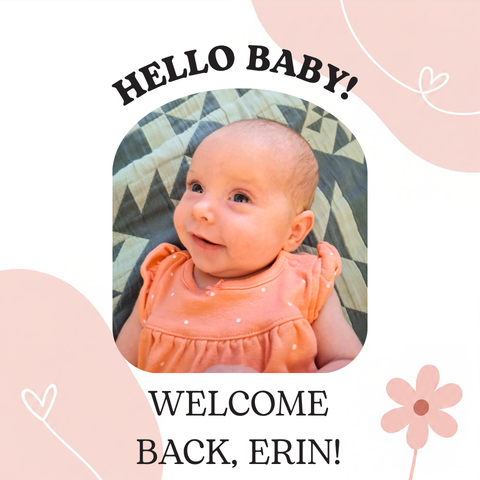
We are so excited to welcome Erin Harlow, Client Operations Manager, back from maternity leave!
She and her family recently welcomed a baby girl into their family, and we couldn’t be happier for them all. Please join us in congratulating Erin on this wonderful new addition!
Medicare Enrollment, IRMAA and More
Your Medicare Initial Enrollment Period
As you approach turning 65, we wanted to share some important Medicare enrollment information. Your window to enroll for Medicare is the seven-month period that begins three months before the month of your 65th birthday and ends three months after it.
Enrollment Window
It is generally advised to sign up on time (if you have not signed up already) to avoid penalties that could prove quite costly over the course of retirement. You can sign up for Medicare online at www.ssa.gov/medicare. Social Security will review your records to see if you qualify for Medicare.
It can be beneficial to enroll in Medicare Part A on time even if you have health coverage already. It won’t cost you anything, and this way, Medicare can serve as your secondary insurance and potentially covers the costs for anything your primary insurance doesn’t cover.
Once you sign up, you will need to choose your coverage. There are two main ways to get Medicare coverage:
1. Original Medicare
Includes Part A and Part B. You can use any doctor or hospital that takes Medicare, anywhere in the U.S.
- If you want drug coverage, you can join a separate Medicare Prescription Drug Plan (Part D).
- To help pay your out-of-pocket costs in Original Medicare (like your 20% coinsurance), you can also add supplemental coverage like a Medicare Supplement Insurance (Medigap) policy.
If you don’t get Part D or a Medigap policy when you’re first eligible, you may have to pay more to get this coverage later. For Part D, this could mean a lifetime premium penalty.
2. Medicare Advantage
An “all in one” alternative to Original Medicare. These “bundled” plans include Part A, Part B, and usually Part D. Most plans offer extra benefits that Original Medicare doesn’t cover, like vision, hearing, dental, and more.
- Plans may have lower out-of-pocket costs than Original Medicare.
- In most cases, you’ll need to use doctors who are in the plan’s network.
Medicare Plan Finder can help you compare all of your options and find what best meets your needs.
Medicare Annual Enrollment Period is October 15-December 7
Medicare’s annual open enrollment period each year is from October 15 to December 7. If you enroll, your coverage will begin on January 1 (as long as the plan gets your request by December 7).
Determining when you must enroll in Medicare can be complicated. Depending on your situation, you may be automatically enrolled, or you may have to proactively enroll. If you must follow the Initial Enrollment Period rules, there is the additional complication of determining when coverage starts. We recommend working with a health insurance agent when enrolling in Medicare.
Appealing an IRMAA Surcharge Based on a Life-Changing Event
Depending on your income, Medicare Part B can include IRMAA surcharges. When you enroll in Medicare Part B, the premiums you pay partially depend on your income reported two years ago on your federal tax return. Therefore, for 2027, your surcharge would be based on your Modified Adjusted Gross Income (MAGI) from your 2025 tax return. If your income is above a certain threshold, you’ll have to pay higher premiums. This higher premium amount is known as your income-related monthly adjustment amount (IRMAA).
However, incomes can change from year to year, so you need a way of requesting reconsideration or appeal of IRMAA surcharges through the Social Security Administration (SSA) if your income changes due to a “life-changing event.” Life-changing events that qualify are marriage, divorce/annulment, death of a spouse, work stoppage, work reduction, loss of income-producing property, loss of pension income, and employer settlement payment. The way to do this is with Social Security Form SSA-44.
What is Form SSA-44?
Form SSA-44 is a form provided by the Social Security Administration (SSA) that you can use to apply for a reduction in your IRMAA. If you’ve been notified that your premiums for either Medicare Part B or prescription drug coverage include an IRMAA, then you can complete and submit this form if you experience a life-changing event that reduces your income.
Who Should Fill Out Form SSA-44?
You may use this form if you received a notice that your monthly Medicare Part B (medical insurance) or prescription drug coverage premiums include an income-related monthly adjustment (IRMAA) and you experienced a life-changing event that may reduce your IRMAA. Life-changing events that qualify are marriage, divorce/annulment, death of a spouse, work stoppage, work reduction, loss of income-producing property, loss of pension income, and employer settlement payment.
You do not need to complete this form if you are not already paying an IRMAA.
How to Submit Form SSA-44
To submit your completed Form SSA-44, you can either mail the form (and your documentation) to your local Social Security office or you can take it in person. You can make a claim at the time you experience any life-changing event that reduces your income. The benefit of visiting an office in person is that you can show your documents to an SSA employee instead of mailing them to the office and being without them for any period of time. We recommend making an appointment with the Social Security office and submitting the form in person.
If you’d like additional information or need any guidance, please reach out to our team or a trusted health insurance agent.
The linked third-party information being provided through this page is strictly as a courtesy. CWM is not liable for any direct or indirect technical or system issues or any consequences arising out of your access to, or your use of third-party technologies, websites, information, and programs made available through third-party websites. You assume total responsibility and risk for your use of these third-party websites.
Before Medicare Open Enrollment Arrives: Why a Medicare Review May Be One of the Most Important Checkups of the Year
For many people, healthcare is one of the biggest expenses they have to plan for in retirement. We spend time reviewing our investments, retirement income, taxes and monthly budgets, but there is one area that is often overlooked: Medicare.
It is easy to understand why. Once you have chosen a Medicare plan that works for you, it can be tempting to simply let it renew each year and move on.
But Medicare plans can change from one year to the next. And so can your healthcare needs.
That is why the weeks leading up to Medicare’s Annual Enrollment Period are a good time to take another look at your coverage.
As a Medicare advisor, I have conversations with people every year who are surprised by what has changed. A prescription that was covered one way may now have different costs. A doctor or hospital may no longer be in a plan’s network. Premiums, deductibles, copays and other out-of-pocket expenses can change as well.
That doesn’t necessarily mean you need a new plan. In fact, sometimes a review simply confirms that the coverage you already have is still a good fit.
Either way, knowing where you stand can give you some peace of mind going into the new year.
The Plan That Worked Last Year May Not Be the Best Fit for Next Year
When you first enrolled in Medicare, you probably made your decision based on the information you had at the time. You considered your doctors, prescriptions, budget and healthcare needs and chose the option that made the most sense.
A lot can happen after that.
Maybe you’ve added a prescription or stopped taking one. Maybe your preferred doctor has changed networks. Perhaps you are traveling more than you used to. Or maybe your healthcare needs have changed and you’re seeing specialists more often.
Your life doesn’t stay exactly the same from year to year. Your Medicare coverage deserves a second look for the same reason.
What Should You Look At During a Medicare Review?
There are several things I recommend paying attention to as Annual Enrollment approaches.
Your Prescription Drugs
Prescription costs can be one of the biggest surprises when a new plan year begins. Drug formularies can change, and the amount you pay for a particular medication can change with them.
It is worth making sure your current prescriptions are still covered and understanding what you can expect to pay under your plan.
Your Doctors and Hospitals
If you have Medicare Advantage, take a few minutes to make sure the doctors and healthcare facilities you use are still part of your plan’s network.
This is especially important if you have a particular primary care physician, specialist or hospital that you prefer to use. A change in network status could affect what you pay or where you can receive care.
What You Really Spend on Healthcare
It is easy to look at a plan’s monthly premium and assume the lowest premium is the least expensive option.
That’s not always the case.
Copays, deductibles, coinsurance, prescription costs and the plan’s annual out-of-pocket maximum all matter. Looking at the total picture can give you a much better idea of what a plan could actually cost you over the course of a year.
Changes in Your Health
The coverage that made sense when you were primarily using your insurance for preventive care may look different if your healthcare needs have changed.
If you’re seeing more doctors, taking additional medications or anticipating a procedure or other ongoing care, those changes should be part of the conversation when reviewing your Medicare coverage.
How Healthcare Fits Into Your Retirement Budget
Healthcare costs don’t exist in a vacuum. They are part of your overall retirement expenses.
Knowing what you can reasonably expect to spend on healthcare in the coming year can make it easier to plan your monthly budget and make decisions about your retirement income.
You Don’t Have to Change Plans
This is an important point that sometimes gets lost during Medicare enrollment season.
A Medicare review does not automatically mean you should change your plan.
Sometimes, after looking at your doctors, prescriptions, benefits and expected costs, you may find that your current coverage is still the best option for you.
That’s a successful review, too.
The goal isn’t to change your Medicare plan every year. The goal is to make sure you understand what you’re paying for and that your coverage still makes sense for where you are today.
Why Start Before Annual Enrollment?
Medicare’s Annual Enrollment Period runs from October 15 through December 7 each year. Changes made during this period generally take effect January 1.
Waiting until the last minute can make the process feel rushed. Starting early gives you time to gather your medications, review your current coverage, ask questions and compare your options.
And sometimes, the most valuable thing you get from a Medicare review isn’t a new plan. It’s confidence that the plan you already have is still doing what you need it to do.
If you’re currently enrolled in Medicare—or will be eligible soon—consider taking some time to review your coverage before annual enrollment begins.
A little time spent looking at your options now could help you avoid an unpleasant surprise later.
Contact Mike Gatteri: 614-568-1324 or 734.252.0064 | [email protected] | TheGatteriAgency.com
This article is intended for educational purposes only and is not a complete description of benefits. Plan availability and benefits may vary by carrier and service area.
Mike is not affiliated or registered with CWM, LLC or Cetera Wealth Services LLC. Any information provided by Mike is in no way related to CWM, LLC or Cetera Wealth Services LLC or its registered representatives.
Additional Resources & Reading
Resource: 10 Questions to Ask Your Advisor
Choosing the right financial advisor can be one of the most important decisions you make for your future. This infographic outlines 10 key areas with questions we think are worth asking, from fee transparency and investment philosophy to succession planning and client service.
Article: Maximizing Medicare: A Strategic Approach to Healthcare in Retirement
Medicare has more moving parts than most people expect, and the decisions you make around enrollment timing and coverage can have a lasting impact on your retirement costs. This piece walks through some key considerations to help you navigate your options.
Have a suggestion? Email us at [email protected].
This newsletter is not intended to provide specific legal, tax, or other professional advice. For a comprehensive review of your personal situation, always consult with a tax or legal advisor.
The opinions contained in this material are those of the author, and not a recommendation or solicitation to buy or sell investment products. This information is from sources believed to be reliable, but Cetera Wealth Services, LLC cannot guarantee or represent that it is accurate or complete.
